Image credit: FINTECHBIZNEWS
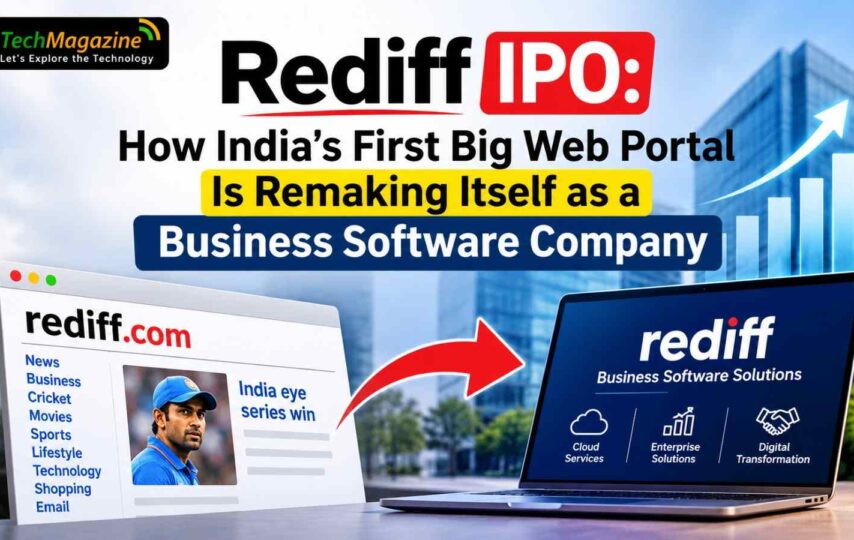
Rediff.com India has filed updated IPO papers for a fresh issue of up to Rs 600 crore, aimed at funding its move into enterprise software, India-hosted cloud email and payments. The Rediff IPO papers were filed with SEBI, BSE and NSE on 14 November 2026. The offer is entirely a fresh issue, with no offer for sale. For many Indians, Rediff means an early email inbox. Now it wants companies to buy its software.
From 1996 portal to AvenuesAI subsidiary
Ajit Balakrishnan founded Rediff in Mumbai in 1996, when the Indian web was still a novelty. It became the first Indian internet company listed on Nasdaq in 2000, then delisted in 2016. By FY24, revenue had fallen to about Rs 36 crore.
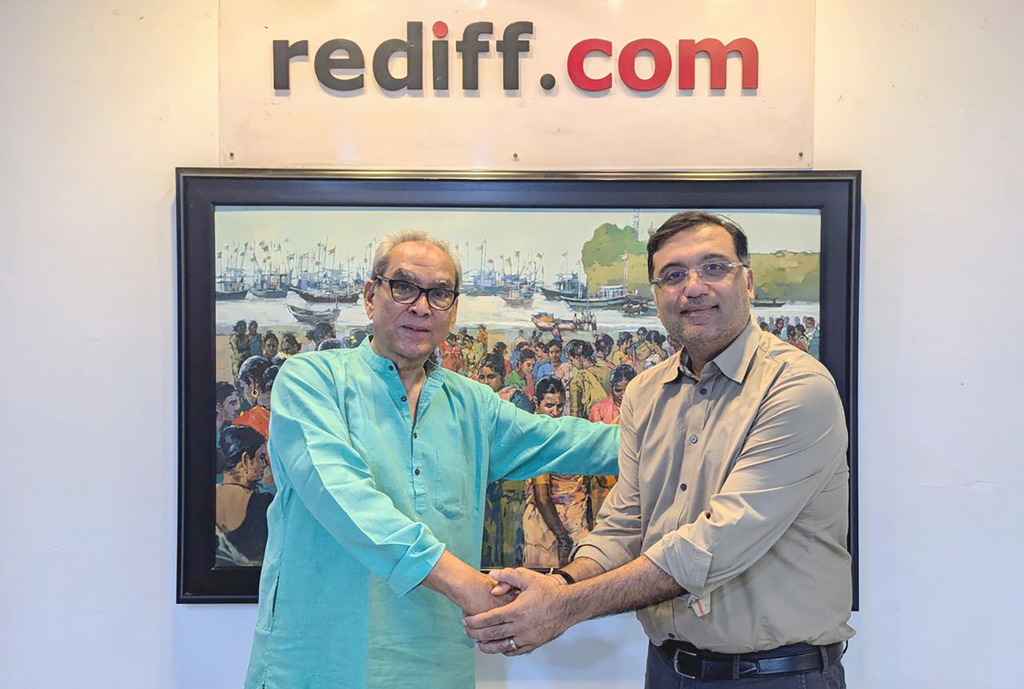
Infibeam Avenues, now AvenuesAI, agreed to buy a 54% stake in August 2024. Its founder and managing director, Vishal Mehta, became Rediff’s chairman and MD two months later. Balakrishnan stayed on as adviser. Mehta studied at Cornell and MIT and formerly worked at Amazon.
In August 2025, AvenuesAI transferred its ecommerce platform infrastructure business to Rediff for Rs 800.39 crore: Rs 400 crore in cash and Rs 400.39 crore in Rediff shares. The parent’s stake rose above 80%.
What Rediff sells to businesses now
Rediffmail Enterprise is the main email product. It offers Indian-hosted company email, custom domains, security features, calendars, contacts and India-based support. AI tools summarise messages, identify action items and extract information.
rCloud handles file storage and management. Rediff Bol provides messaging and team collaboration. Rediff One brings communication, productivity and commerce under one enterprise platform. It includes the ecommerce infrastructure acquired from AvenuesAI in 2025. ERP, CRM and HR modules are planned.
According to the prospectus, platform data is hosted only in India. Rediff continues to run Rediff News, its homepage and Rediff TV, an AI-generated video news service.
RediffPay is the company’s UPI app. NPCI granted it a third-party application provider licence in February 2025, with Axis Bank as PSP bank. Final NPCI approval came in December 2025, followed by closed user group testing.
The Nayara episode and the sovereignty pitch
The EU sanctions were imposed on Nayara Energy in July 2025, which has a 49% stake in the company held by Russia’s Rosneft. Microsoft suspended Outlook and Teams for the business.
Nayara went to the Delhi High Court and resorted to Rediff for temporary email address. Rediff continued to move new mail, but failed to get old data from Microsoft’s cloud. Microsoft restored services within days, before the court hearing.
The incident sparked a larger discussion on Indian companies using foreign technology vendors. The concern is now being used by Rediff to argue the case for India-hosted systems.
The numbers in the prospectus
Revenue from operations stood at Rs 133.59 crore in FY26 compared to Rs 37.23 crore in FY25. EBITDA (excluding other income) was Rs 65.24 crore. Operating cash flow swung to an inflow of Rs 160.50 crore from an outflow of Rs 61.29 crore in FY25. Revenue for the quarter ended June 2026 was Rs 58.38 crore and EBITDA (excluding other income) was Rs 39.43 crore.
Much of this was from the ecommerce infrastructure business bought from AvenuesAI, which is not just organic growth. As of 30 September 2026, Rediff had approximately 19,179 enterprise customers in the government, education, pharma, energy, healthcare, IT and insurance sectors. Retention was about 80%.
It has 152.46 million Rediffmail accounts, but not active users. It claimed to have 90.83 million annual active users, 46.62 million average monthly visits and 42% of its content traffic coming from outside India for its news, TV and homepage services.
Where the IPO money goes
Rediff plans to use about Rs 408 crore for technology development, platform expansion, marketing and branding. This comprises Rs 94.50 crore capital expenditure on Rediff One’s planned ERP, CRM and HR modules.
The remaining funds after issue expenses can be used for acquisitions and other corporate uses, subject to regulatory restrictions. The Rediff IPO is meant to support the Rediff One, RediffPay and Rediff TV.
What still has to be proved
RediffPay and Rediff TV are still in the early commercial phase. A lot of people visiting a website doesn’t necessarily translate to a lot of paying customers. Rediff has to prove that it can generate revenue from its consumer base.
Another challenge is enterprise customers. Will current email customers be willing to purchase additional products, and can these additional purchases be converted to recurring subscription revenue? There is a need for a reason for the buyers to opt for Rediff over the existing software vendors.
The acquisition makes it more difficult to measure. It has altered the size of the business, and a straight comparison between the previous year and the current year might mask as much as it shows.
Conclusion
For years, Rediff has been a nostalgia punchline, often framed as a teasing question: do you still use Rediffmail? Now its route back runs through company email that stays in India.
It is hardly the stuff of a glossy technology trailer. Nobody gets misty-eyed over a calendar app or file storage. Yet office email is a daily utility, and the location of its data can matter when a foreign provider switches it off. The Rediff IPO rests on an unfashionable promise: your company’s inbox should keep working, on terms it can control.